When the amount of loss is the question.
Independent property insurance appraisal, grounded in how buildings are actually put together.
Discuss your claim
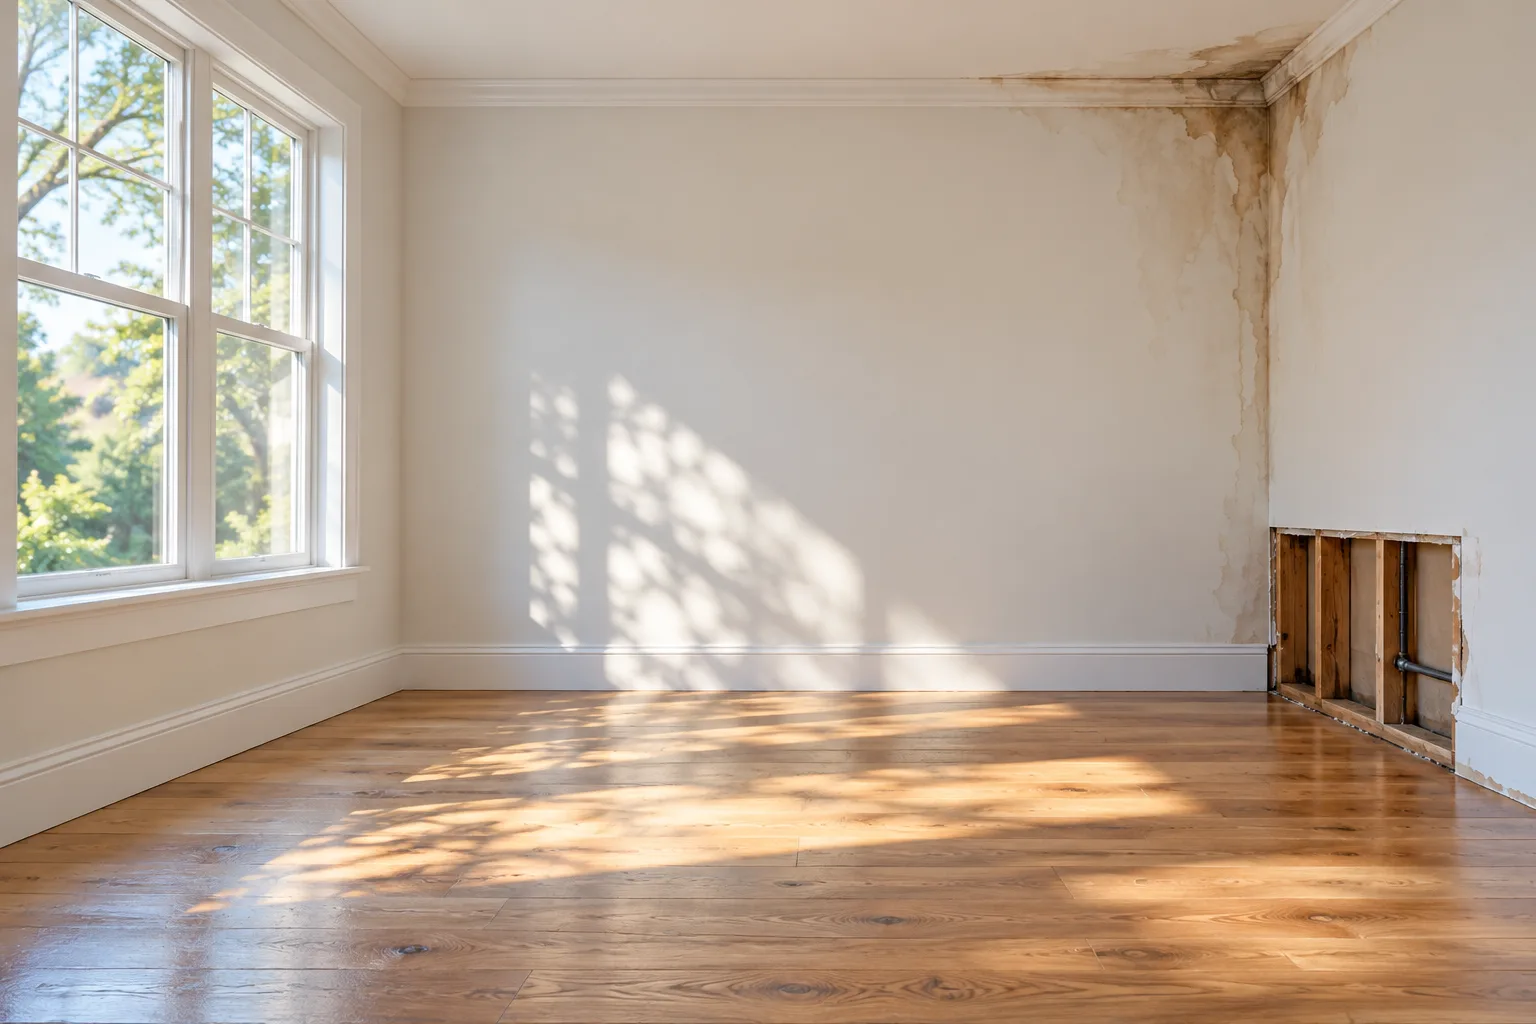
The surface is
a starting point.
Materials. Layers. Repair scope.
Photographs show the visible condition. Measurements and construction details add context to the work involved.
CP4 considers those details alongside the documentation and the agreed assignment.
Discuss an appraisalA defined role.
A detailed assessment.
You and the insurer may agree there is a covered loss, yet disagree about the cost to repair it.
A property policy’s appraisal provision may provide a process for addressing that difference. CP4 can serve as a named appraiser to inspect, scope, and assess the amount of the loss under the assignment.
The work starts with the property and the documentation: what is affected, which construction details matter, and what the repair scope calls for.
Appraisal is not a substitute for legal advice. The policy, applicable requirements, and the specific dispute determine whether appraisal is appropriate.
Start with the
right question.
Is the disagreement about the amount?
Differences in the repair scope, quantities, or cost may be relevant to appraisal. Share the point of disagreement so the assignment can be considered.
Is the disagreement about coverage?
Questions about a denial, exclusions, legal rights, or bad faith should be discussed with a qualified attorney. CP4 does not determine coverage or provide legal representation.
Is an estimate what you need first?
A detailed Xactimate estimate may be the appropriate service. See estimating
What the assignment
can involve.
Every policy and file is different.
The scope is agreed before work begins.
- 01
Start with the file.
Share the property location, current estimates, and where the numbers differ. We first establish whether the assignment fits.
- 02
Look at the details.
The agreed scope guides the inspection, documentation, measurements, and estimating work.
- 03
Build the assessment.
Relevant construction details and repair scope are considered together, with clear supporting documentation.
- 04
Know the next step.
Receive the agreed appraisal or estimating work. Appraisal steps follow the policy and the assignment.
The formal appraisal process may include appointing appraisers, selecting an umpire, and documenting an award. Specific steps, deadlines, and effects depend on the policy and applicable requirements.
Before you
take the next step.
General background from the Texas Department of Insurance home insurance guide.
Can appraisal resolve a denied claim?
Appraisal generally addresses the amount of a loss, rather than whether a policy provides coverage. Coverage denials, exclusions, and legal disputes should be discussed with a qualified attorney. We can help identify whether the issue you describe fits the services CP4 provides.
What should I have ready?
For an initial conversation, a short description of the property, its location, and the point of disagreement is enough. If the assignment proceeds, relevant estimates, photographs, measurements, and policy or claim documents may be requested through an agreed channel. Please do not put sensitive documents into the contact form.
Does sending the form appoint CP4 as my appraiser?
No. An inquiry starts a conversation. An appointment or engagement requires a separate agreement and any steps required by the policy. Sending the form does not extend or pause policy deadlines.
Let’s look at where the numbers differ.
Share the property’s location and a short description of the disagreement. That is enough to start the conversation.